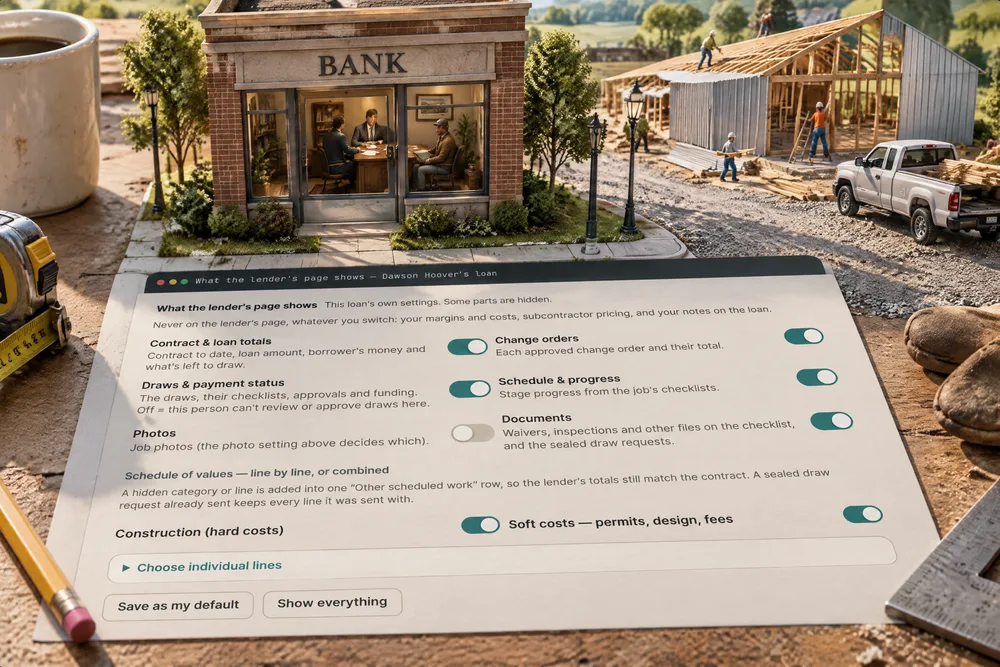
In the loan's Lender & access tab, What the lender's page shows decides what the bank opens from its link. Six parts are switches: Contract & loan totals, Change orders, Draws & payment status, Schedule & progress, Photos and Documents. Below them is the schedule of values — show a whole category or a single line on its own, or combine it. A combined line is never dropped: it's added into one "Other scheduled work" row, so the bank's totals still match the contract. Save as my default and every new loan starts from your choices. Some things are never on the bank's page, whatever you switch: your margins and costs, your subs' prices and your notes on the loan. Made only for post-frame and barndominium builders — whose buyers mostly build on a construction loan.
Also called: what the lender sees · hide budget lines from the bank · lender page settings · lender view template · bank visibility · hide photos from the lender · combine schedule of values lines · lender page privacy
Switch off any part of the bank's page, loan by loan
Try itIn Lender & access, What the lender's page shows has six switches: Contract & loan totals, Change orders, Draws & payment status, Schedule & progress, Photos and Documents. Each loan keeps its own settings, and the line beside the heading tells you whose you're looking at — this loan's own, your account default, or everything. Above the switches it says plainly what's never on the bank's page: your margins and costs, subcontractor pricing and your notes on the loan. On Dawson Hoover's shop, Photos is off. Switching off Draws & payment status also means nobody on that link can review or approve a draw there.
Prairie Hills sends its own inspector and has no use for 300 photos of the slab — but the only page you could give it showed everything.
A loan officer who gets exactly what her bank asked for has nothing to chase. The builder sets it once per loan, in the tab where he already hands out the links, so it's part of setting the loan up — not a favour he has to remember later.
A line you keep back is combined, never dropped
Switch a line off and it doesn't vanish from the bank's page — it's added into one row that says what happened: Other scheduled work — 1 line combined by the builder. Every other line keeps its number, and the total is still the contract. On Dawson's loan the $19,616.44 Insulation line sits in that row, and the total still reads $286,400.00.
Take a line off a schedule of values and it no longer adds up to the contract — and a page that doesn't add up gets a phone call before it gets a draw.
Banks don't argue with a schedule that adds up. A loan officer checks the schedule of values against the contract before anything else; a combined line still reconciles and says it was combined, so there's nothing to call you about.
Whole categories, or one line at a time
Try itUnder Schedule of values — line by line, or combined, switch a whole category — Construction (hard costs) or Soft costs — permits, design, fees — or open Choose individual lines and switch any single line. A line inside a category that's off greys out, because the category already decides it.
You only want one number kept to yourself, and the choice on offer is show the bank everything or show it nothing.
Builders think in lines; banks think in categories — so both are there. The broader switch always wins, which means there's never a question about which setting the bank's page is following.
Photos off means no Photos tab at all
Switch Photos off and the bank's page has no Photos tab — not an empty one. It opens on the same header and numbers, with Draws, Progress, Schedule of values, Documents and Activity. When Photos is on, which job photos the bank sees — every one, only those shared with the customer, or none — is still the Photos the lender sees setting in the loan details.
An empty Photos tab on the bank's page reads like something is being kept from it.
An empty tab makes a careful reader ask what's missing. When a part is switched off the page is drawn without it, so the bank sees a complete page, not a page with a hole in it.
Keep the contract figures off the first screen
Switch off Contract & loan totals and the contract, the loan amount, the borrower's money and everything worked out from them stay off the page. It opens on Built, Funded and Retainage held, and each draw still shows its own amount.
Every person you send a link to opens the job on the contract price and the loan amount, whether their job needs them or not.
Not everyone on a link needs the contract price. An inspector checking progress or a title clerk confirming a date can do the job from progress and payments, and the builder decides who reads the big numbers.
Status without the file, when that's all a bank needs
Switch off Documents and the checklist still tells the bank what's done and what's missing — but no file comes with it, and the sealed draw requests can't be opened from that link either. On draw 2, the unconditional waiver for draw 1 reads Submitted, with nothing attached.
The bank only needs to know the waiver is in, but the only way to show that was to hand everyone on the loan the waiver itself.
"Is it in?" and "send me the file" are different questions. Some banks only ask the first; answering it without handing every document to every person on the loan keeps the page to what that bank asked for.
A draw the bank already has stays exactly as sent
These settings change the bank's page from now on. They never change a draw request that's already gone: each one is sealed when it's sent and keeps every line it was sent with. Dawson's draw 1 went out before Insulation was combined, so in the bank's copy Insulation is still line 9. How the sealed draw request is put together lives on the draws page.
You change what the bank sees today, and the draw it funded last month quietly changes underneath it.
A bank has to be able to trust its own file. If a setting could rewrite a document the bank already funded, nothing in the file could be relied on — so what was sealed stays sealed.
Set it once as your default
Try itSave as my default makes this loan's switches and categories the starting point for every new loan, and for any loan without settings of its own. Use my default puts a loan back on it. With nothing saved anywhere, a loan's page shows everything — exactly as it always did.
Every new loan starts out showing everything, and setting it up again is the step that gets skipped in a busy week.
Nobody sets the same six switches carefully on the tenth loan. Most builders work with a handful of banks that want much the same thing — save it once and every new loan starts right without anyone remembering to.
Your default carries the switches, never one job's lines
The next loan — Marcus Yoder's barndominium — opens Following your account default: Photos off, like Dawson's. But every line of its schedule is shown on its own, because individual lines belong to one loan. A default carries the six switches and the categories.
A copied setting tries to hide a line the next job doesn't even have — or hides one it shouldn't.
A default that copied one job's lines would hide the wrong things on the next job. Lines change from job to job; what a bank wants to see mostly doesn't.
Everyone on the loan opens the same page
The settings belong to the loan, so every link on it shows the same page: Janet Kohler the loan officer, Brent Sauer at the draw desk, Roy Detweiler the inspector, and Dawson himself. Each still has their own link, which you can switch off on its own.
The loan officer and the inspector are looking at different versions of the job and arguing about which one is right.
When everybody at the bank looks at the same page, nobody has to ask what the other one saw. One set of choices per loan is easy to keep straight — for the builder and for the bank.
- 1Open the job's Construction loan card, go to Lender & access, and find What the lender's page shows.
- 2Switch off any of the six parts and the bank's page simply doesn't have it — no tab, no tile, no empty box.
- 3Under Schedule of values, switch a whole category off, or open Choose individual lines and switch one line off; it joins the Other scheduled work row.
- 4Save as my default — new loans, and loans without their own settings, start from it. Use my default puts a loan back on it.
- 5Everyone with a link to that loan — loan officer, draw administrator, inspector, borrower — opens the same page.
- 6A draw request already sent stays exactly as it was sealed; the settings shape the page from now on.
Every bank asks for something slightly different. One wants every photo; another sends its own inspector and has no use for three hundred pictures of a slab. One reads the contract figures first; another only wants to know whether the draw's checklist is done. And some of what's on a builder's job is nobody else's business. A page that shows a bank everything, or nothing, fits none of them. So the builder chooses, loan by loan, and the bank's page is put together from those choices before it is sent — a part that's switched off never leaves at all. A line kept off the schedule is combined rather than deleted, because a loan officer adds the schedule up against the contract before anything else, and a page that doesn't add up earns a phone call instead of a draw.
- One fixed lender page for every bank, whatever it asked for.
- Keeping a line back broke the schedule's totals — so nothing got kept back.
- Setting up the same choices again on every new loan.